Projects

Projects

Quantitative finance, research and software. Each write-up covers the question, the method, the results and what I would do next.

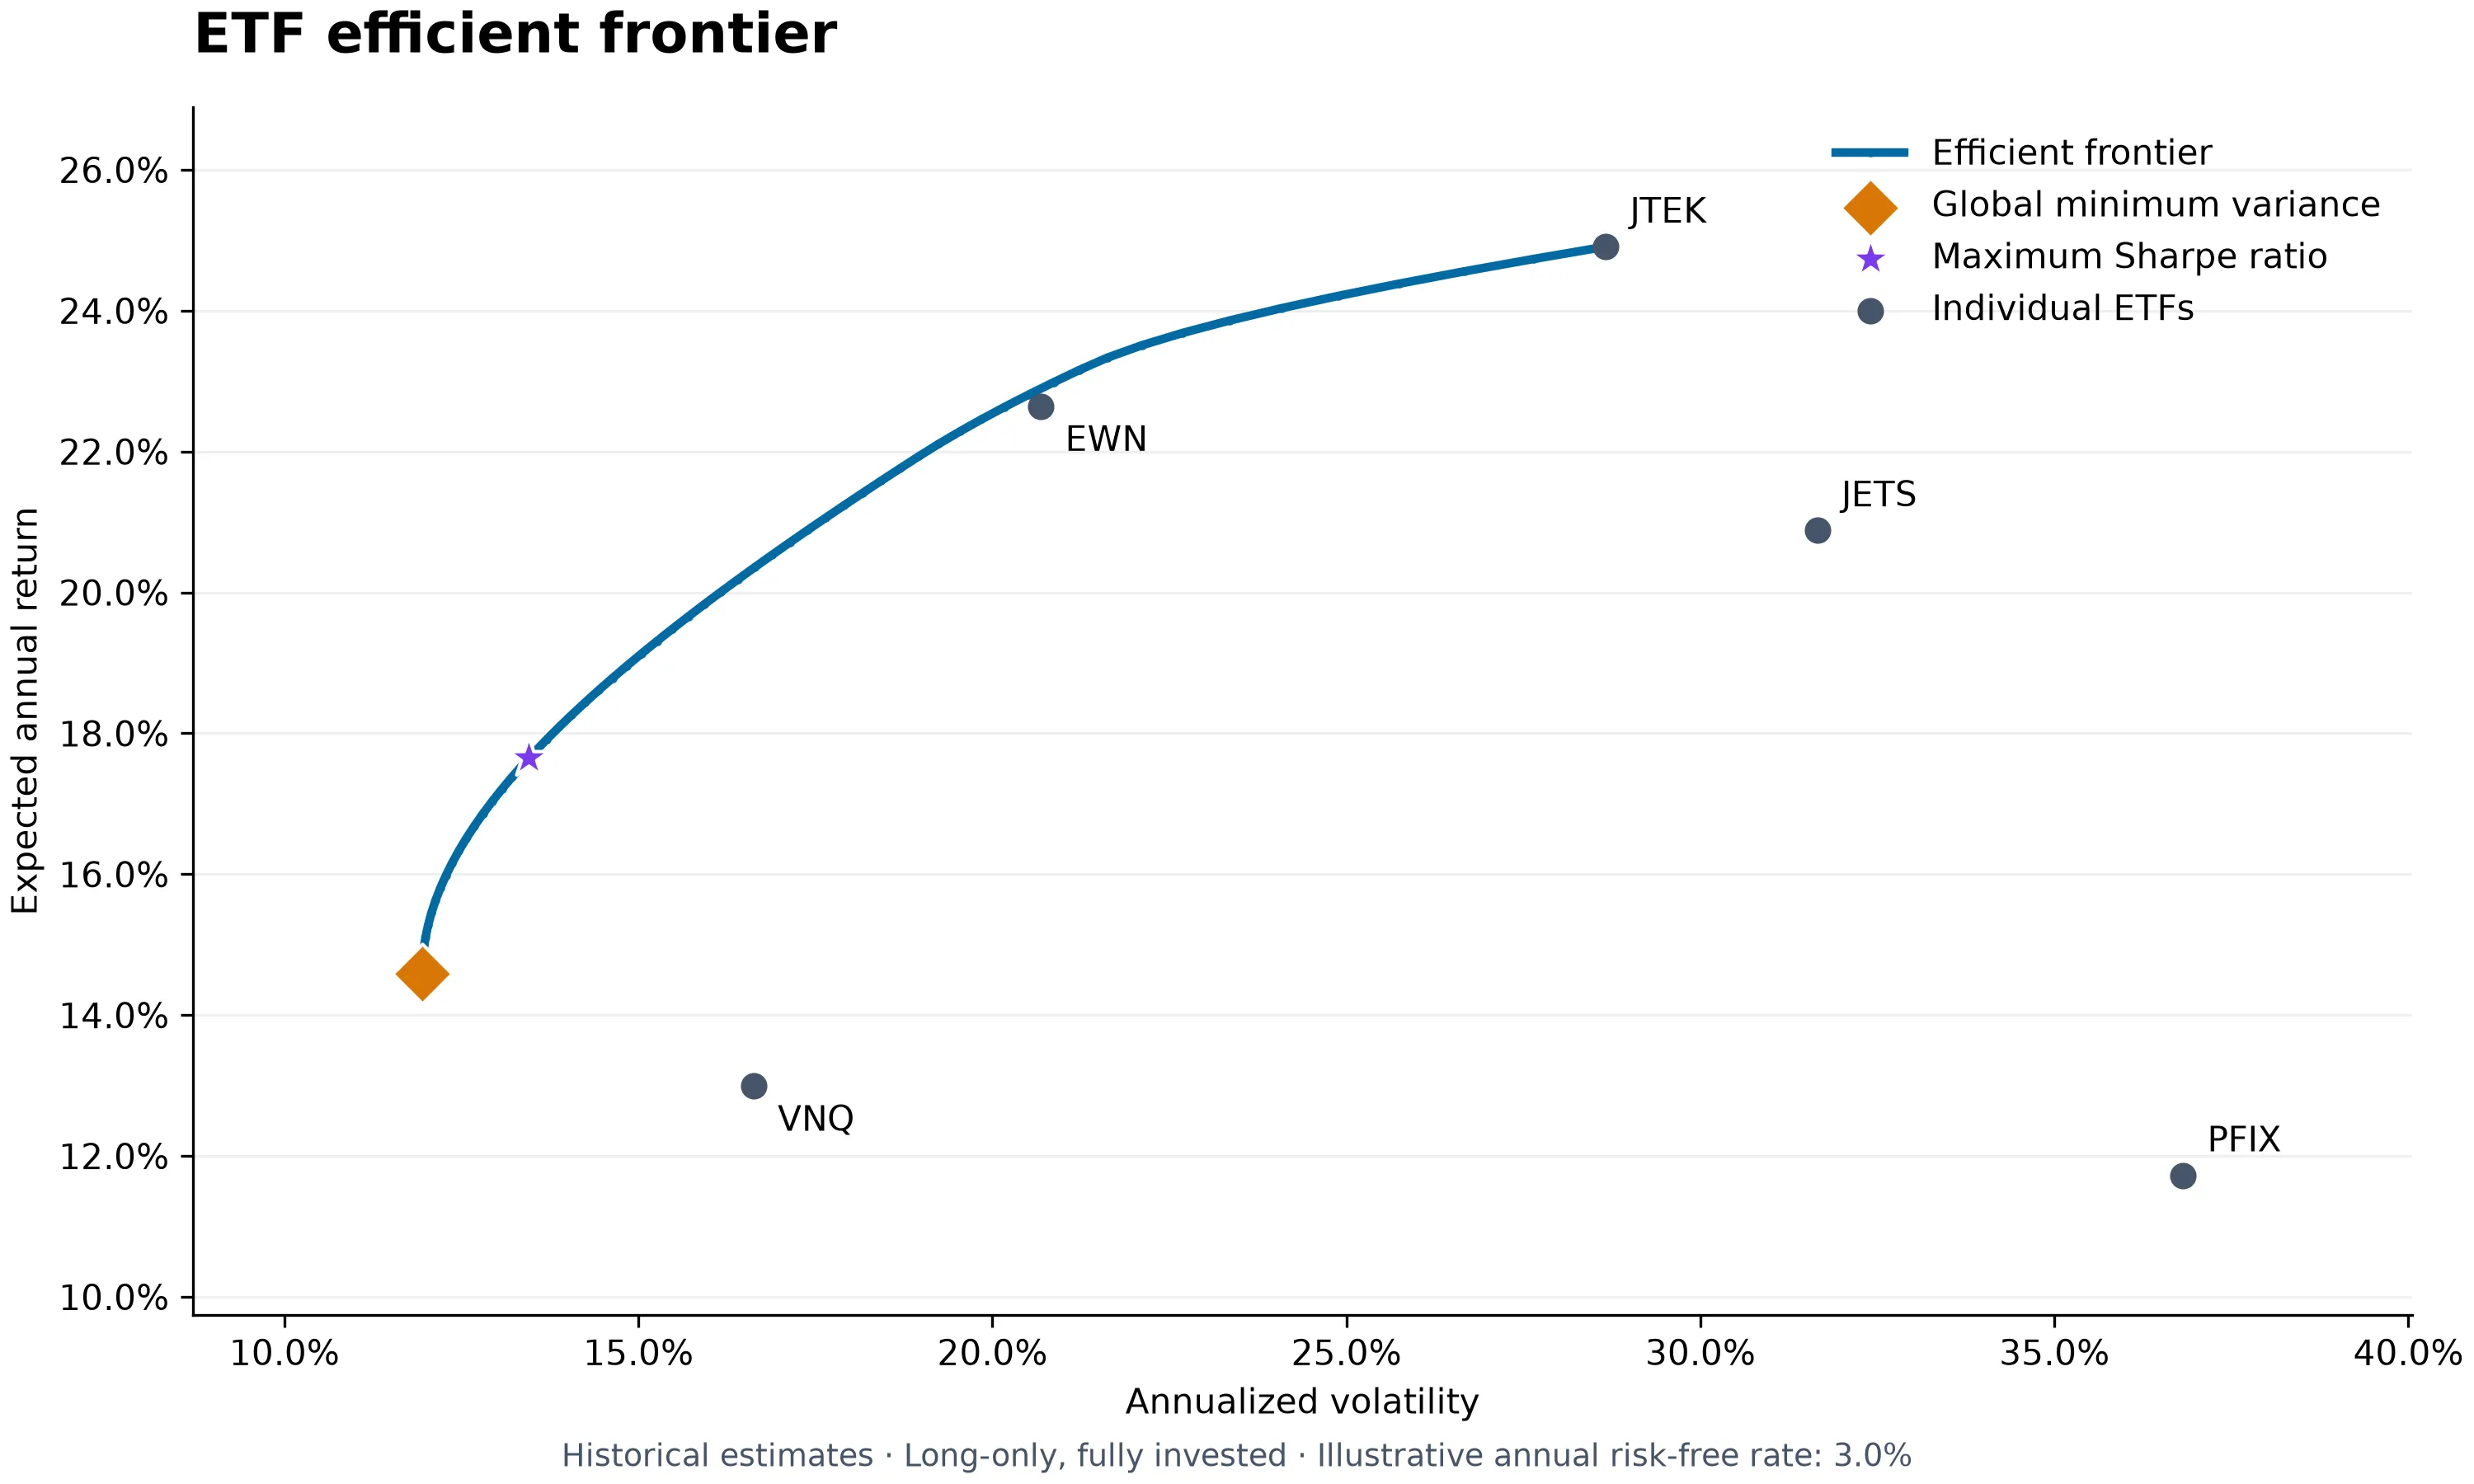
Mean–variance optimisation of a five-ETF universe with SciPy, an efficient frontier, and a chronological out-of-sample backtest against equal-weight and single-asset benchmarks. Modular, tested and reproducible from a saved data snapshot.

Out-of-sample Sharpe: 1.32 for minimum variance vs 0.59 for the in-sample maximum-Sharpe portfolio
  • Python
  • NumPy
  • pandas
  • SciPy
  • pytest

CourseBeaver

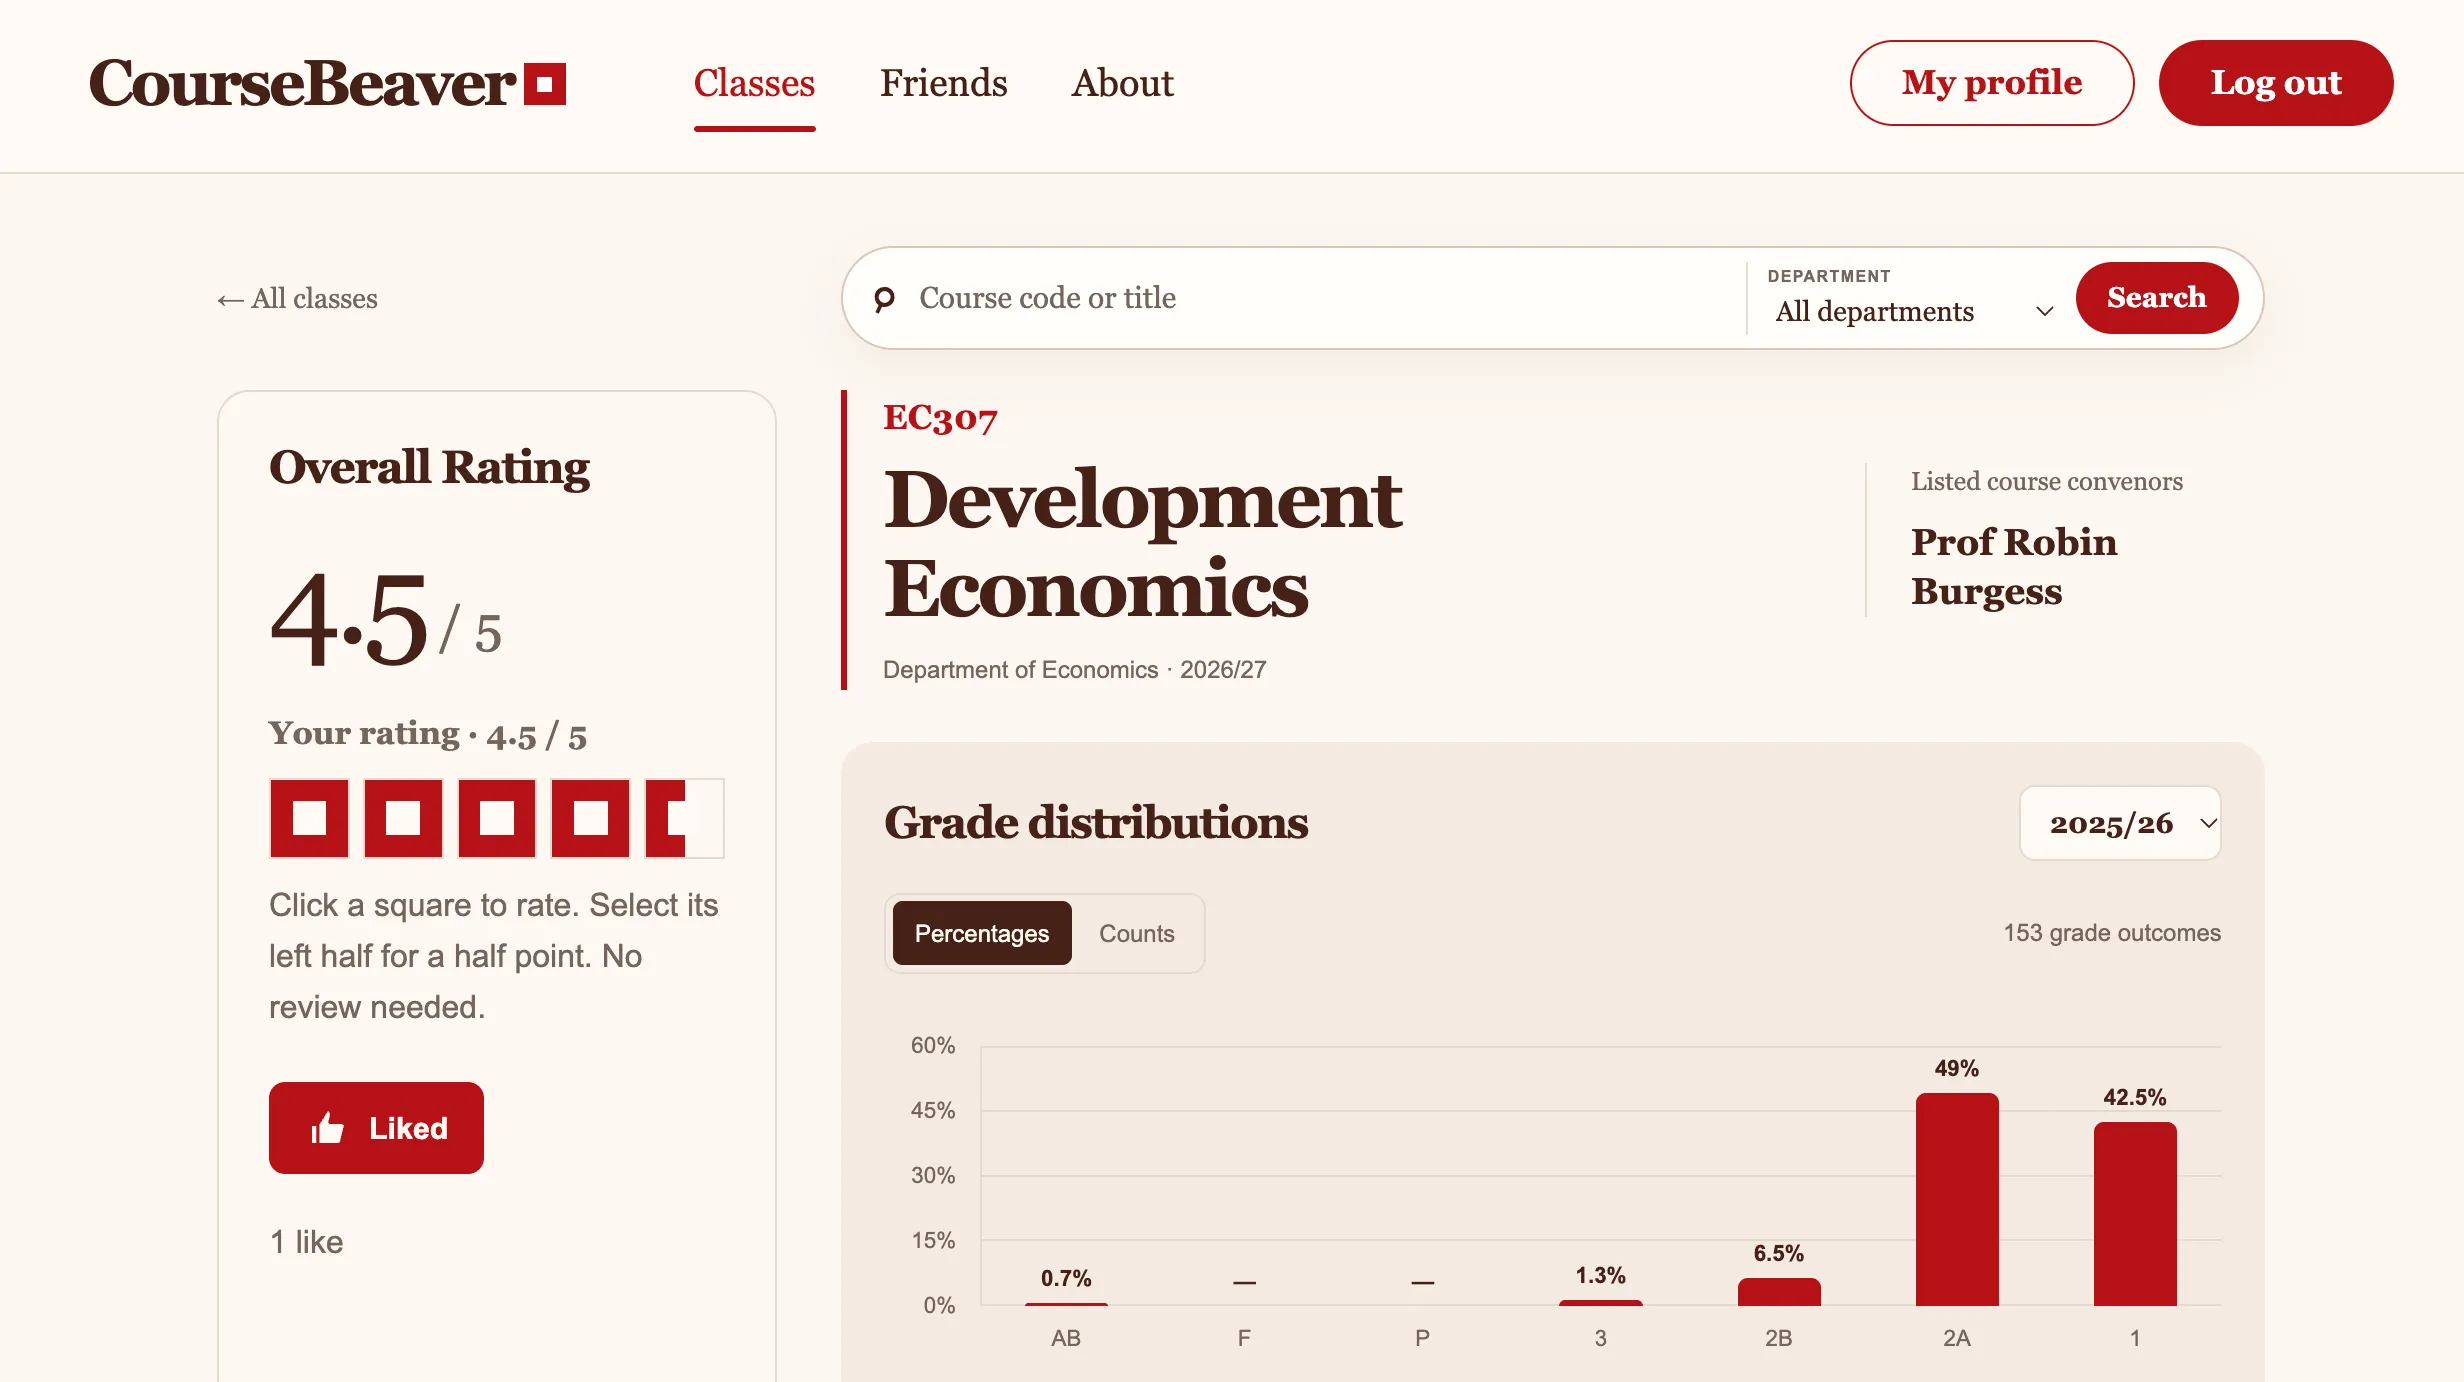
A full-stack course discovery platform for LSE students, with course ratings and reviews, grade-distribution visualisations, and friend-based class discovery. Includes email authentication and database-level access control.

  • Course ratings and written reviews
  • Grade-distribution visualisations
  • Friend-based class discovery
  • Verified email sign-up with database-level access control
  • Next.js
  • React
  • TypeScript
  • PostgreSQL
  • Supabase

Independent student project, not affiliated with LSE. Source code private.

Currently building

In progress

Option Pricing Library

In progress

Binomial lattice and Monte Carlo pricers validated against Black–Scholes, with Greeks and convergence analysis and a C++ pricing core called from Python.

  • Python
  • C++
  • NumPy